
Public Liability Insurance - How Much Cover Do I Need?
06 October 2026
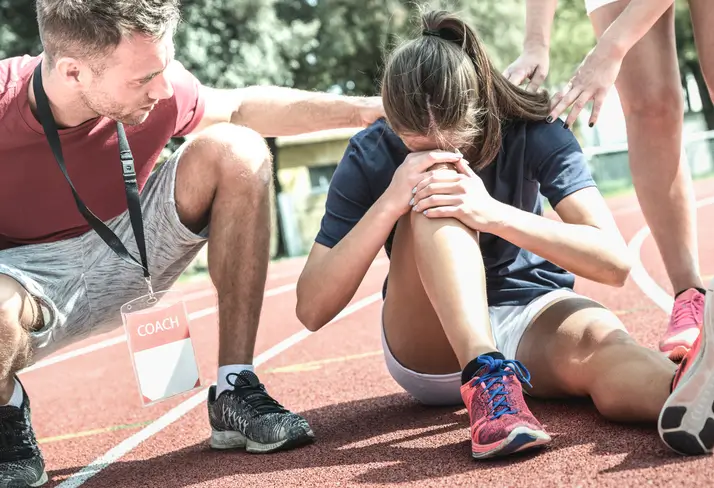
If a client, class participant or member of the public says your work caused an injury or damaged their property, they may claim against you for compensation. Public Liability insurance is there to help provide financial protection for this claim and any resulting legal costs.
Different businesses may require different levels of cover. In this guide, we’ll help you understand how much cover may be appropriate for your circumstances. We’ll also explain what Public Liability insurance typically includes.
What is Public Liability insurance?
Public Liability insurance for sports coaches and personal trainers can protect you financially if someone claims you injured them or damaged their property while you were working. For example, it might cover compensation and legal costs if a client is hurt during a session, or if you accidentally damage equipment at a venue you hire. What is covered depends on the activity and your chosen cover level.
This is different from Personal Accident insurance. Public Liability cover is for claims made against you by other people, whereas Personal Accident cover can help if you are injured yourself. A Public Liability claim usually involves someone alleging that you were at fault or negligent.
Public Liability insurance is not a legal requirement, but many gyms, venues and governing bodies will expect you to have it before you can work with them. If you train clients or coach groups, consider what it could cost you if someone claimed you were responsible for their injury or damaged property.
What can Public Liability insurance cover?
Public Liability cover will typically help with:
- Injury to other people: Compensation if someone, such as a client, spectator or member of the public, claims you caused their injury while you were working. For example, a client might say they were hurt because you set up equipment incorrectly.
- Damage to other people's property: Compensation if you accidentally damage property belonging to someone else, such as equipment or facilities at a gym or venue you use. An excess may apply to these claims.
- Legal costs: The cost of defending a claim made against you, if the insurer agrees to handle it. These costs are usually paid in addition to, or as part of, your limit of cover, so check how your policy treats them.
- Products you sell or supply: Some policies include cover if a product you supply, such as equipment or supplements, causes injury or damage. Check whether this applies and what is excluded.
Every policy has a limit of cover, which is the most the insurer will pay for a claim. Some gyms, venues and governing bodies ask for a minimum limit, so check what they require before you choose.
At Insure4Sport, your limit of cover and covered sports are listed in your policy schedule, the document that summarises your cover. The insurance booklet explains what is and is not covered.
Public Liability cover levels explained
Different Public Liability policies offer different cover levels. The examples below show levels you may come across, but availability, pricing and suitability depend on the policy and the activities you undertake.
|
Public Liability cover level |
When it might suit |
|
£1.5 million |
Often chosen for lower-risk coaching or personal training work. |
|
£2.5 million |
Often chosen by coaches and trainers working in higher-risk activities. |
|
£5 million |
Sometimes required by gyms, venues or professional bodies. |
|
£10 million |
Occasionally required for larger events, some venues or contracts with higher cover requirements. |
There is no single level that suits every coach or trainer. A one-to-one trainer and a coach running large group sessions may face different risks. Think about the number of participants, the equipment used, the activities and how serious an injury could be.
If you work in a gym or sports venue, ask whether it requires a minimum amount of cover. A professional body or client contract may set its own amount too.
Some policies also include cover for injuries between participants, for example if one person in your group session injures another. Check whether this is included if you coach groups or contact sports.
Public Liability insurance does not always include Professional Indemnity insurance, which can help with certain claims about your professional advice or instruction, such as a client saying a training plan you designed caused an injury. Check whether it is included, what it covers and the maximum amount payable.
For policies by Insure4Sport, check your quote and policy schedule for the amount of Public Liability cover and whether Professional Indemnity or cover for injuries between participants is included or selected. The insurance booklet explains this in detail.
Real claims, real lessons
Even an ordinary training session can sometimes lead to a significant compensation claim against you.
That doesn't mean accidents are inevitable or that you should worry about every session. Good planning, appropriate supervision, risk assessments and sensible equipment management can all help reduce the likelihood of something going wrong.
The following real Insure4Sport case studies show the potential size of compensation claims and the role Public Liability insurance plays.
Equipment left against a wall
During a fitness class, a piece of equipment was left standing against a wall rather than being put away. Later in the session, it was knocked over and fell onto a participant's foot. The injury took over three months to heal, and the resulting claim ran into tens of thousands of pounds.
A trip hazard at a venue entrance
A visitor tripped over an advertising board positioned near a venue entrance, injuring their knee badly enough to need ligament surgery. The liability claim reached well into the tens of thousands of pounds.
A collision in a children's session
During a children's multi-sport session, two participants collided. One child needed hospital treatment, and the claim reached well into the tens of thousands of pounds.
Why do Public Liability limits matter?
A single serious claim can involve compensation for injuries, lost earnings, ongoing care and legal costs. If a claim is worth more than your limit of cover, you could be personally responsible for the difference.
Ask what your limit covers, whether legal costs are included within it or paid on top, and whether any excess applies. Also check what is not covered, such as injuries between participants or claims about your professional advice, if these are not included.
Regular checks of your equipment, venue and group size can help reduce the chance of an incident and give you a record of the precautions you took. For practical steps, see our sports coaching risk assessment guide. Our claims process guide explains what happens after an incident is reported.
What can make a Public Liability claim more expensive than expected?
A claim can cost more when an injury lasts a long time or legal costs build up. The amount someone asks for is not always the amount they receive.
- A serious or lasting injury: The person may need ongoing treatment or lose income because they cannot work.
- Legal costs: A case that is challenged or goes to court may cost more to resolve.
- A longer process: Legal fees and other costs can build up while a claim is being resolved.
Public liability insurance FAQs
Do venues or governing bodies set a minimum cover level?
Some gyms, leisure centres, sports venues and governing bodies require a particular level of Public Liability insurance cover as part of your permission to work.
The minimum can vary by organisation, activity and contract. Some venues ask for limits in the millions of pounds, so confirm the exact requirement before choosing a policy.
Before deciding on a cover level, check your contracts or confirm insurance requirements with the venues or organisations. It's better to choose the right level of cover before you start work than discover your policy doesn't meet a contractual requirement afterwards.
How much Public Liability cover do I need?
No one level suits everyone. When working out how much cover you’ll require, a sensible starting point is to consider:
- The coaching you do: Think about the type of coaching or personal training you provide, the equipment involved, and the inherent risks of it.
- Where you work: Is it a private studio, clients’ homes, a public sports venue, a gym, or a mix of places? If you work at another venue, do they require you to have a minimum level of Public Liability cover?
- Who you work with: Some groups may carry a greater risk.
Would a higher limit give you more flexibility? If you work across different venues or often take on new types of work, a higher limit may help you meet your requirements without making frequent policy changes.
Public Liability insurance FAQs
Is Public Liability insurance a legal requirement for sports coaches?
Public Liability insurance is generally not required by law for a self-employed PT or sports coach in the UK. However, many gyms, venues, clients and governing bodies will ask for it before you can work with them, so check their requirements before choosing your level of cover.
If you employ staff, check whether you need Employers' Liability insurance, which covers certain claims by employees injured at work. There are exemptions, so see the government guidance.
What's the difference between Public Liability and Professional Indemnity insurance?
These two types of cover protect you against different types of claims:
- Public Liability insurance can help with covered claims from other people who say your work caused an injury or damaged their property.
- Professional Indemnity insurance can help with certain claims about the advice, instruction or service you provided.
The types of claim each one covers can overlap or differ, so check the policy wording. You might buy the two together or separately, so check the activities covered and the maximum amount available for each.
Does my venue's insurance cover me as a freelance coach?
Not necessarily. A gym's insurance may cover the gym without covering you as a freelance PT. Ask the venue what its policy covers and whether you need your own Public Liability insurance, and get written confirmation if it says you are included.
What isn't covered by Public Liability insurance?
What is left out varies by policy. Areas to check include:
- Injuries to your employees, which usually need Employers' Liability insurance
- Claims from family members, if the policy excludes them
- Damage to property you are looking after or using, unless the policy says it is covered
- Extra responsibilities you accepted in a contract that would not otherwise be yours
- Fines or penalties
If you teach a contact sport, also check whether injuries between participants are covered (see below).
Can I increase my Public Liability cover level later in the policy year?
You may be able to increase your cover partway through the year. Ask your insurer whether it agrees, what it will cost and when the higher amount would start, and get the change confirmed in writing.
What is participant-to-participant liability?
This means a claim after one person in your class or session injures another. Policies treat these claims differently, and some leave them out, particularly in contact sports, unless you add the cover separately.
This matters for contact sports and activities involving tackles or throws. Check which sports, people and types of incident are covered before you run those sessions.
Public Liability cover by Insure4Sport
At Insure4Sport, Public Liability cover can help protect you if someone claims your work caused them an injury or damaged their property. The amount of protection depends on the limit of cover you choose, so check what any gyms, venues or governing bodies you work with require, and think about the activities you run and the number of people you coach.
If you already have a policy, check your policy schedule and the insurance booklet to see what's included. If you're looking for cover, get a quote for sports insurance. To compare how the two types of cover work, read our guide to Personal Accident insurance.
Please note the information provided on this page should not be taken as advice and has been written as a matter of opinion. For more on insurance cover and policy wording, see our homepage.
Get a quick quote for Sports Insurance
Get A QuoteRelated Posts
Insure4Sport is a
 Insurance Services product


©Copyright Ripe Thinking Limited 2026.
Insure4Sport® is a registered trademark and a trading name of Ripe Insurance Services Limited which is Authorised and Regulated by the Financial Conduct Authority No.313411. Registered office: One Stockport Exchange, Railway Road, Stockport, United Kingdom, SK1 3SW. Registered in England No. 04507332.